Third-Party Payment Requests in Agent-Assisted Crypto Orders
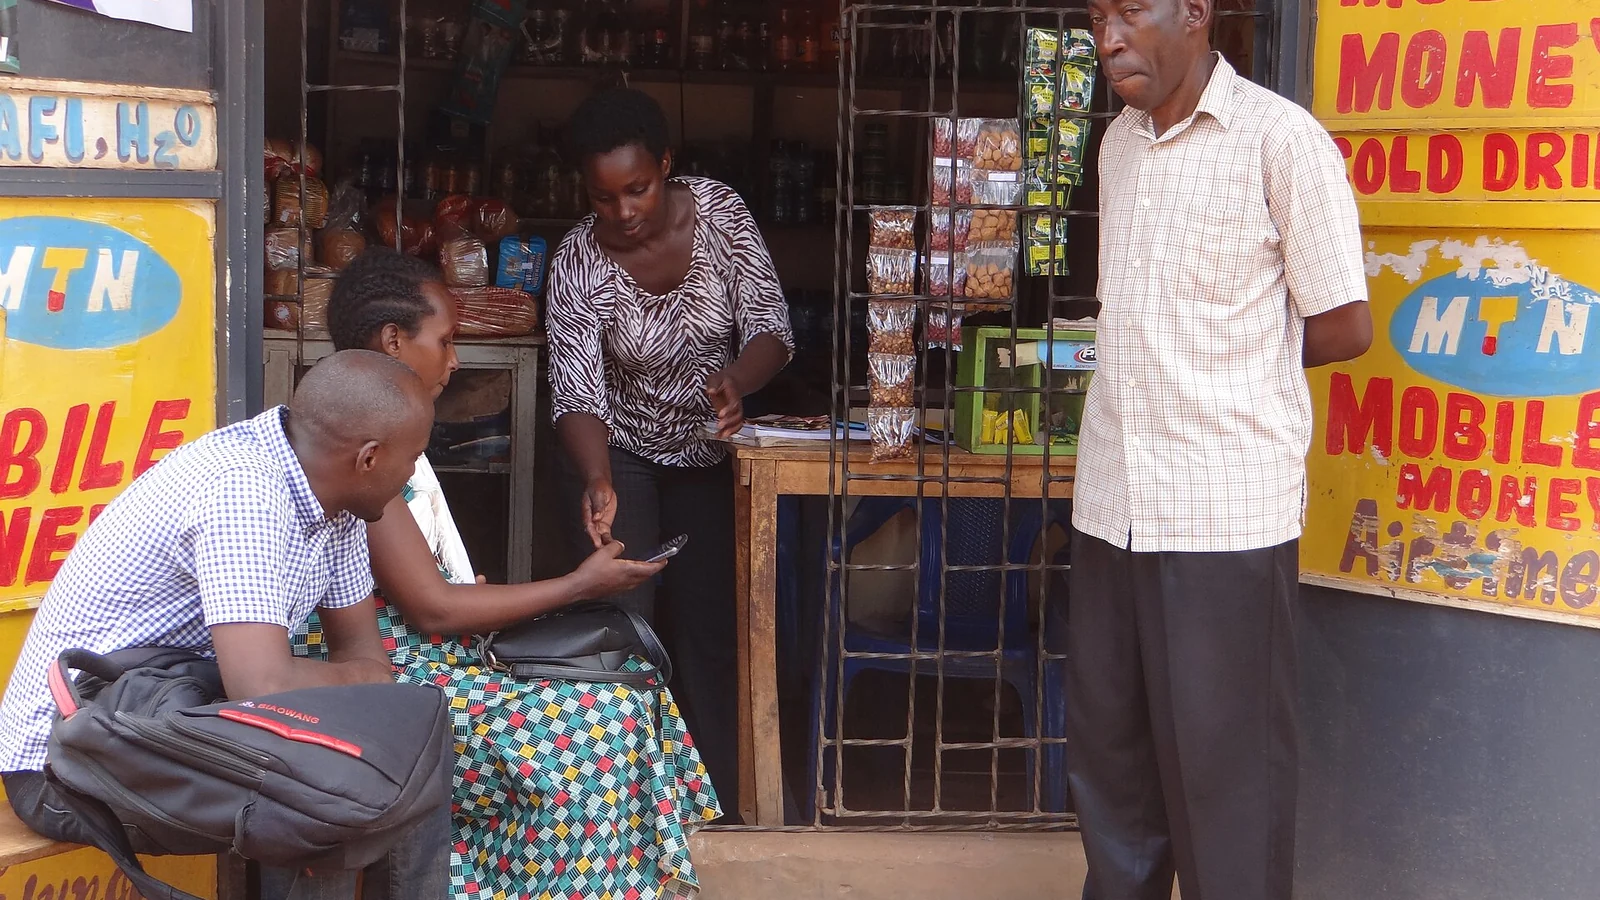
A buyer agrees to an order but receives instructions to pay an unfamiliar name.
A mobile-money counter provides context for identifying the authorized recipient of a local payment.
The problem behind third party payments
The explanation may be that the agent is busy, the account belongs to a partner or local banking requires a workaround. Each claim may be plausible in conversation without being authorized by the platform.
What the systems record about counterparty risk
In many P2P settings, payer and beneficiary names are part of the controls that identify the two parties. Moving funds to a third person can break that connection and complicate a dispute. The risk depends on the payment method and the platform's actual instructions.
A focused example of third party payments
Suppose the payment address is suddenly described as a relative's account. The buyer's uncertainty concerns ownership, not only whether the account is able to receive funds. Pause, document the original and revised instructions, and ask the platform whether that specific third-party route is permitted. Do not let a passing payment timer settle the question.
A different name changes the underlying question
The risk of a third-party payment is not limited to whether the funds will reach a bank account. It also affects whether the payer, seller and marketplace can later prove which trade the transfer belonged to. A beneficiary outside the approved order may be a legitimate person, but that alone does not connect them to the escrow record. A buyer who follows private instructions can end up with a genuine bank payment that the marketplace has no reason to recognize as performance of the original order. The relevant evidence is permission for that precise payment route, not the intermediary's familiarity with it.
Imagine that the contact first provides an account belonging to the named trader, then asks for a transfer to a colleague because the first account is unavailable. Before paying, preserve the initial instruction and obtain clarification through the authenticated trading service. If the order itself has not changed, do not assume that a message can amend it. Also check the actual payment method: a reversal-prone wallet transfer and a bank transfer can create different disputes even when the recipient's name appears to match. The decision should be made before a transfer is initiated, when a mistaken choice can still be avoided.
How to test the claim
Compare the beneficiary on the financial app with the identity shown in the live order. If the name differs, pause and use the platform's own support channel. Save both versions of the instruction, including the moment it changed. A supposed P2P crypto agent may describe a workaround as standard practice, but an introduction does not amend escrow terms. Shiftal Coin's educational material explains how P2P counterparties and payment methods interact.
- Record the original beneficiary before responding to a new receiving-account instruction.
- Compare the proposed third party with the identities displayed in the current marketplace order.
- Ask official support whether the specific payment route is recognized for that transaction.
Why surface signals mislead
The most dangerous response is to assume that escrow covers any payment made in connection with an order. Escrow may protect the crypto inside the platform while leaving an outside bank transfer beyond the order's recognized workflow.
Putting the review into practice
A changed recipient creates a new decision, not a minor continuation of the old one. Do not rely on reassurance from the person proposing the change; require verification from a channel you reached independently. Name abbreviations and unrelated account holders call for different responses, as explained in how to classify a payment-name mismatch.
#ThirdPartyPayments #CounterpartyRisk #Escrow
You might also like
 Learning & Education
Биоревитализация: первичная оценка состояния лица перед процедурой
Желание сделать кожу более увлажнённой или ровной не отвечает на вопрос, какая процедура действительно нужна. Сухость, ощущение стянутости и изменение текстуры имеют разные причины, а эстетический запрос нельзя заменять обещанием универсального &laqu...
 P2P | Practical reading
When a P2P Sender Name Does Not Match the Trading Account
A third-party sender changes the risk profile. A beneficiary mismatch changes the identity of the transaction even when the amount, currency and promised delivery date stay the same. Pause, compare identities and seek platform-native resolution. &...
💬 Comments (0)